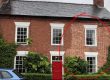
I’ll never forget that day. I was pushing a trolley round a supermarket when my managing agent rang. That wasn’t a surprise, because it was that morning that he was meeting my main lender’s valuer to show him four properties I’d just bought for cash, and I was arranging finance to get my money back out again. But what my managing agent told me was one of the craziest things I’ve ever heard.
The four properties were all together in one single terrace, and my managing agent was standing on the pavement waiting when the valuer pulled up in his car. But rather than getting out, he had a quick look through the windscreen, wound down the window and said words to the effect of, you’ve got to be joking. He actually said it in a much stronger way than that, but I won’t repeat exactly what he said. He didn’t even get out. He just drove off. And when he got back to the office he told his employer, the lender, that none of these properties were suitable security under any circumstances.
Sometimes people ask me what you do if you get a down valuation. But this wasn’t a down valuation. This was a no valuation at all valuation. And the problem for me was that I’d just bought them for cash. So in this post I’m going to tell you what I did about it and what happened next.
How I came to own them
My managing agent was investing in property himself and he wanted to release some of his capital. He owned four properties that had housed him and various members of his family over the years, including his grandmother, and he rang me up and said, would you like to buy them? I can’t give you a massive discount, but I can help a little bit on the price. And you know they’re good properties, I’ve lived there, my gran’s lived there, I’ve looked after them.
It just so happened that at that time I’d refinanced some of my properties and I did have some cash which I wanted to put back into the business. And I knew the properties. He was very proud of them, he’d shown them to me on several occasions, and I knew they were very well looked after and very well managed. So I had no hesitation in saying yes. They were good properties, they had good tenants, they had good cash flow, and it was hard to imagine there would be a problem with them.
For whatever reason, I think I was just busy and distracted, I didn’t think about raising finance on them until after I’d completed. And it was at that point that I got in touch with my mortgage broker, who put in the application to my main lender, who then sent out the valuer, who then drove off.
What the valuer saw
So what was it that the valuer saw which I hadn’t seen? What I think put him off was the area. To be fair, it was a regeneration area, and behind this particular terrace the local council had compulsorily purchased another terrace, which they’d knocked down and which in the short term was being used as a grassed area. But I knew, and I knew it had been going on for some time, that the council were talking to a local developer about selling them the land so that they could build a brand new housing estate.
The thing I never really understood is that the valuer clearly saw that as a bad thing, whereas I saw it as a very positive thing. But on the day the valuer went out there, the deal between the council and the developer hadn’t been done, and so there I was with the problem. Four new properties, all purchased for cash, and no way that I could get a mortgage.
Don’t panic
So I rang my broker, I had a little bit of a rant, and then said, but what are we going to do about it? And he said, very wisely, Peter, don’t panic. We’ll put the application in with a different lender, because a different lender will send out a different valuer. It’s going to cost a bit more in fees, but let’s just see what happens.
And that’s what we did. About six weeks later another valuer arrived at the properties, but this time the valuer actually got out of the car. This time he took his clipboard, walked around the properties and made notes. Then he went back to the office and produced a mortgage valuation for each of the properties, with a sensible valuation figure, and the new lender lent me the money. I was able to pay myself back a large chunk of the money I’d put in to buy them.
And shortly afterwards the council did sell the land to the local developer, and if you went there now you’d find an estate of newish quality homes, a lot of them owned by first time buyers and second steppers. The area is unrecognisable and very much improved.
The real problem was the timing
Now to be honest, I think the first valuer was a little bit over the top in his assessment of the area. Yes, it wasn’t the greatest, but it certainly wasn’t the worst either. But of course he was entitled to his opinion, and his job was to protect the bank. The problem for me was that I didn’t find out his opinion until after I’d actually bought the properties. I was more than committed. I’d bought them and I’d paid cash for them. And if the second valuer had agreed and also said no, I’d have had four properties, all paid for with cash, which I couldn’t borrow against.
It’s a similar problem to the one I told you about in an earlier video, where I showed you the property which turned out to have dry rot under the bathroom carpet, which cost me £40,000 to put right. I’d bought that property as part of a portfolio, and by the time I found out about the problem I’d actually bought the portfolio, so I was well and truly committed.
And that’s the point. In both cases the information arrived after I was committed, when the only thing left to decide was how to cope with it. There was no walking away, there was no pulling out of the deal. The deal had been done.
What I’d do differently now
So with that experience, is there anything I’d do differently now? Yes. The first thing I’d probably do is put the mortgage application in earlier, before I was committed. Now, I honestly can’t remember why I did delay on those four properties. Maybe it was because I knew them and I was being a little bit complacent. But it certainly wasn’t a strategic decision, because in my model I’d much rather use the bank’s money than use my own. And that’s not the only reason I’d put my mortgage application in earlier. It’s also in case of problems like this, where there may be a hiccup that causes problems and delays, and it’s best to know that before you are committed. In this instance I was fine, because the second valuer was happy. But if he hadn’t been, I would have had a real problem.
The second thing I’d take out of this experience is not to rely on the mortgage valuation instead of a survey. Some people think, well, I won’t have a survey, I’ll rely on the lender’s valuation, and maybe 95 times out of 100 that’s absolutely fine. But if you’re one of the five times it isn’t, then you’re stuffed, aren’t you? As a surveyor, I have to say, always get a survey, although I accept there may be times in real life when it turns out you probably didn’t need it.
Without being disrespectful to mortgage valuers, and I used to be one, by the way, you can see from the way the first mortgage valuer reacted that just because it says something on a piece of paper doesn’t necessarily mean it’s true. You need to do enough due diligence to be satisfied that you know what the property is like, and not just rely on assumption and other people’s observations. But what you don’t want to do is start your due diligence once the report has come back saying you shouldn’t have bought the property. That can be a very uncomfortable position to be in, and one you should never find yourself in.
The big takeaway
So the big takeaway for me is don’t take anything for granted, don’t be complacent, do get your mortgage application in early, and if, which is highly likely, you need other professional advice, make sure you get that early as well. Make sure you know exactly what you’re buying before you commit to the property.
And if you are paying cash like I did, I’d even suggest instructing your own valuation from a local valuer before you buy the property. Because if that flags up any problems, then at least you’re aware, and you can start dealing with them before you’ve actually spent good money on the property.
Here’s to successful property inspecting.
Peter Jones
Author, property investor and ex-Chartered Surveyor
 PS. If you’d like a practical guide to the most common defects in residential investment property, the things most buyers walk straight past on a viewing and what each one actually means, my book 63 Common Defects covers them. You can find it at thepropertyteacher.co.uk/63-common-defects-investment-property-spot/